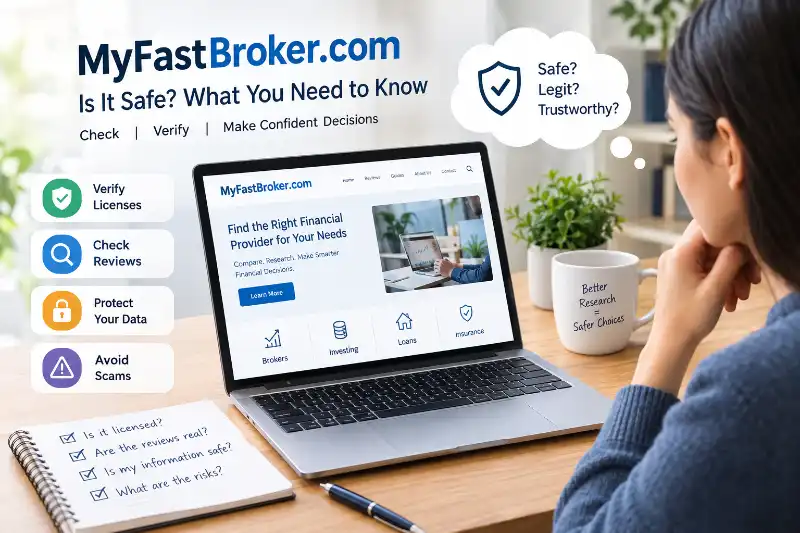
If you have come across MyFastBroker.com, you may be wondering what the website actually does. Is it a place where you can open a brokerage account? Can you use it to trade stocks? Or does it mainly share information about financial services?
These questions matter because a website that discusses brokers is not always a broker itself. The difference can affect where you send your personal details, who handles your money, and which company you need to check before making a financial decision.
In this first part, we will look at the website’s purpose, whether it offers direct trading, and what its public information can tell us about its identity. The goal is simple: help you understand what you are dealing with before you take the next step.
What Does MyFastBroker.com Actually Do?
If you have visited the site but still cannot tell what service it provides, start with its published pages rather than its name. A website can discuss financial products without selling them or handling customer accounts.
To understand MyFastBroker.com, the key is to separate what the website says it does from what you can independently confirm.
What financial topics does the website cover?
Begin with the site’s homepage, service descriptions, and any articles or comparison pages it publishes. Look for the types of financial products it discusses and the people it aims to help.
For example, a website might explain how different brokers compare, describe account fees, or discuss features that customers should consider. That would make it an information resource. It would not, by itself, mean the website can open an account or execute a trade for you.
When reviewing MyFastBroker.com, check whether its actual pages support the services it appears to describe. Do not assume that every possible financial service is available simply because the site’s name includes the word “Broker.”
What this means for you: Identify the specific service or information you came to find. Then confirm that the website actually provides it.
Is it an information website or a financial service provider?
This is an important distinction, especially if you are thinking about investing.
An information website helps you learn about financial products or compare providers. A financial service provider may offer accounts, accept applications, hold customer assets, or carry out regulated activities. These are different roles, and one company can sometimes perform more than one of them.
The website’s contact information can help clarify the distinction. MyFastBroker.com’s published contact information has described the site as not opening accounts, executing trades, or managing funds. Treat that as the site’s own statement, not independent proof of every aspect of its business.
You can also examine its terms, disclosures, and links to outside companies. If an external provider handles the actual account or transaction, that provider’s identity matters.
Example: Suppose you read about a stockbroker on an information website and then follow a link to another company’s application page. The company accepting your application—not necessarily the site where you first read about it—is the one you need to identify before submitting your details.
The answer: Do not judge a website’s role by its name alone. Check what it says it does, what its pages actually offer, and which company handles any financial service you want to use.
Can You Open an Account or Trade Directly Through MyFastBroker.com?
If you are visiting the website because you want to buy stocks or start investing, you need to know whether you can complete those actions there or whether you must use another company.
The word “Broker” can create the wrong impression. The only safe way to settle this question is to check the services the website actually offers.
How can you tell whether direct trading is available?
Look for an account registration page, a trading dashboard, account funding instructions, and clear information about the company that would hold or manage your account.
Then review the website’s terms and disclosures. These should help explain who provides the service and who is responsible for customer accounts.
If the website only publishes articles or directs visitors to other providers, that does not establish that it offers direct trading.
Here is a simple example:
- You read an article about stock trading on MyFastBroker.com.
- The article links to a separate financial company’s website.
- You are asked to create an account on that company’s platform.
In this situation, you should identify the company named on the account application and review its terms before proceeding. Do not assume that MyFastBroker.com operates the linked platform.
What if the website sends you to another provider?
An external link does not automatically mean something is wrong. Financial information websites can direct readers to third-party services. The important question is whether the destination is clearly identified and whether you understand the relationship between the two websites.
Before registering, check the destination address, the legal company name, the fees, and the terms that apply to your account. Be especially careful if the company name changes during registration or payment instructions do not match the provider’s published details.
The answer: Confirm who will actually open and manage the account before providing financial information or depositing money. If you cannot identify that company, pause until you can.
Is MyFastBroker.com Legit? What Can the Evidence Confirm?
Perhaps you have already visited the site and want to know whether it is trustworthy. That is a fair question, but a simple “yes” or “no” may not tell the whole story.
A website can exist and publish real content without every claim about its business being independently verified. To assess MyFastBroker.com fairly, separate confirmed facts from statements made by the website itself.
What can you verify about the website’s operator?
Start with the information the website publishes about the business behind it. Check its About page, contact details, terms of use, privacy policy, and any legal or company disclosures.
Look for a consistent company name and a clear explanation of who is responsible for the website. If a legal entity is named, compare that name with reliable public records where available.
Pay attention to what the evidence actually shows. A contact form confirms that a way to contact the website is provided; it does not, on its own, establish the identity of the people running the business. Likewise, a published company name should not be treated as independently verified until you can match it to a reliable source.
If the operator’s identity cannot be established from the available information, report that limitation clearly. An unclear identity is a reason to investigate further, but it is not automatic proof of fraud.
What do domain records and HTTPS tell you?
Two common checks can help you understand a website, but both have limits.
Domain records may provide information about when a domain was registered, its registrar, and whether some registration details are publicly available. Privacy protection can hide the registrant’s personal information, so a hidden name does not prove wrongdoing.
HTTPS protects the connection between your browser and the website. You can usually recognize it by the padlock or security indicator in the browser’s address bar. It helps protect information in transit, but it does not prove that a business is honest, financially regulated, or safe to invest with.
Consider this example: you visit a website with HTTPS and find that its domain has been active for several years. Those details can tell you something about the site’s technical setup and history. They cannot, by themselves, confirm that the business behind it is trustworthy.
For a sound assessment, compare several types of evidence instead of relying on a single signal.
How should you interpret the findings?
Use these three categories when reviewing the website:
- Confirmed: A claim supported by a reliable, independent source.
- Website-stated: Information published by MyFastBroker.com that you have not independently confirmed.
- Unresolved: Information for which you could not find enough reliable evidence.
This approach helps you avoid two common mistakes: trusting a website simply because it looks professional, or calling it a scam just because some information is missing.
The answer: Judge MyFastBroker.com by the evidence available, not by its name, appearance, domain age, or HTTPS alone. If important details about the business remain unclear, do not treat those details as verified.
Does MyFastBroker.com Need a Financial License?
If you are trying to find out whether MyFastBroker.com is properly licensed, one detail matters first: what financial activity does the business actually carry out?
A website that publishes financial articles may have different legal requirements from a company that executes stock trades, gives regulated investment advice, or arranges loans. The word “Broker” in a domain name does not settle that question.
When is a financial license required?
The answer depends on the service, the business model, and the laws that apply.
For example, a company that carries out securities transactions may need to register as a broker-dealer. A firm providing certain types of investment advice may need to register with the SEC or a state regulator. Mortgage lending, insurance, and other financial activities can have their own rules.
For MyFastBroker.com, start with the activities described on its website and the services it actually provides. Its contact page says it does not open accounts, execute trades, or manage funds. That statement is relevant, but it does not independently settle every possible question about the site’s activities or legal obligations.
How should you interpret a missing license record?
Do not assume that every financial website must appear in the same regulator’s database.
A publishing website may not need the same registration as a broker-dealer. A financial company may also be listed under its legal business name rather than its website name. You need to identify the entity and activity before drawing a conclusion.
At the same time, if a company claims to provide a regulated service but you cannot confirm its registration where one is required, do not ignore the gap. Ask the company for its full legal name and registration details, then verify them through the relevant regulator.
The answer: First establish what the business does. Then determine which rules apply to that activity. A missing listing alone does not prove fraud, but an unverified claim of regulatory approval should never be taken on trust.
How Can You Verify a Financial Company Behind a Recommendation?
If MyFastBroker.com mentions a broker, investment adviser, lender, or insurance provider, you may want to check that company before signing up. The most useful approach is to verify the actual provider, not just the website where you found it.
Which official database should you use?
For US financial services, the right database depends on the type of provider.
- Stockbrokers and brokerage firms: Use FINRA BrokerCheck to look up firms and registered professionals.
- Investment advisers: Use the SEC’s Investment Adviser Public Disclosure (IAPD) database. It provides registration information and access to adviser filings.
 Investor+1
- Futures and derivatives firms: Check the relevant registration information through the National Futures Association’s BASIC system.
- Mortgage providers: Depending on the company and the service, use the Nationwide Multistate Licensing System (NMLS) and relevant state regulator resources.
- Insurance providers: Check the appropriate state insurance department’s records.
These databases serve different purposes. Do not use a stockbroker database to make a final judgment about a mortgage lender or an insurance company.
What should you compare in the results?
Once you find a record, compare the provider’s legal name with the name shown on the website or application. Check the registration status, the type of services covered, and any available disciplinary information.
For example, suppose an article recommends a company called ABC Investments, but the application names ABC Financial Services LLC. That difference does not automatically mean something is wrong. It does mean you should establish whether the two names refer to the same business and which entity will provide the service.
Be careful with search results that merely mention a regulator. A company displaying a regulatory logo or claiming to be “SEC approved” is not the same as a verified registration. The SEC itself warns that it does not endorse particular firms, investments, or financial products.
The answer: Identify the provider’s exact legal name, choose the appropriate official database, and confirm that the record matches the service being offered. If the names or registration details do not line up, resolve the difference before proceeding.
Can You Rely on MyFastBroker.com’s Reviews and Rankings?
If you are using a website to compare financial providers, the main concern is whether its reviews give you enough information to make a fair choice. A confident recommendation is not the same as a well-supported one.
You do not need to assume that every review is biased. Instead, look at how the review reaches its conclusion and whether you can check its claims.
How can you tell whether a review is fair?
Start with the facts that could affect your decision. For a stockbroker, these might include trading fees, account minimums, available investments, withdrawal rules, and customer support. For a mortgage provider, interest rates, closing costs, and repayment terms may matter more.
A useful review explains its comparison criteria and provides sources for important claims. It should also mention drawbacks rather than focusing only on benefits.
Ask yourself:
- Is the information recent enough for the product being discussed?
- Does the article link to the provider’s official fee schedule or terms?
- Does it explain why one provider ranks above another?
- Does it discuss meaningful disadvantages as well as benefits?
- Does it disclose sponsorships or affiliate relationships where relevant?
For example, imagine a review calls one broker the cheapest option but does not mention its account fees or withdrawal charges. You cannot judge the full cost from that claim alone. Check the provider’s current fee schedule before deciding.
Does an affiliate link mean a review is unreliable?
Not necessarily. Some websites earn money when readers click a link or sign up for a service. That arrangement does not automatically make a review inaccurate, but it can be relevant to how you assess the recommendation.
Look for a clear disclosure explaining whether the website may earn a commission. Then check whether the review provides enough evidence to support its ranking.
MyFastBroker.com describes itself as an educational and comparison resource. Its claims about editorial independence or compensation should be treated as statements from the website unless you can confirm them independently.
The answer: Do not choose a financial provider just because a review gives it a high ranking. Compare the underlying facts, check current terms, and consider any relevant commercial disclosures.
What Happens to Your Information When You Follow a MyFastBroker.com Link?
If you are concerned about your personal information, the key question is where that information goes. Reading an article is different from filling out an application on another company’s website.
What does MyFastBroker.com’s privacy policy say?
MyFastBroker.com’s published Privacy Policy states that the website does not actively collect or store visitors’ personal information and that information sent through email or phone is used to respond to inquiries. It also describes its approach to information sharing and security. These are the website’s stated practices, not an independent audit of its systems.
If you want to contact the site, read the policy and consider what information is actually needed for your message. You generally do not need to include bank details, account passwords, or identity documents in a routine inquiry.
What if a link takes you to another website?
When you follow an external link, check the address bar before entering any information. The destination may have its own operator, privacy policy, and data practices.
Before submitting a form, find out:
- Which legal company is collecting the information?
- Why does it need the information?
- Will the information be shared with other companies?
- Is the form on the provider’s genuine website?
- Can you review the privacy terms before agreeing?
For example, if you click a link to compare loans and land on a page requesting your income, phone number, and Social Security number, stop and confirm who operates the form and how the information will be used. Do not assume that the destination follows the same privacy policy as the site you left.
The answer: Review the policy of the website collecting your information, not just the website that linked to it. If you cannot identify the recipient or understand why sensitive details are needed, do not submit them yet.
What Should You Do If You Cannot Verify a Claim or Provider?
Sometimes you check the website, read its terms, and search the relevant public records, but an important question remains unanswered. That does not automatically mean you have found a scam. It does mean you should avoid treating the claim as proven.
What if the company will not explain who it is?
Ask for the provider’s full legal name, official website, relevant registration details, and written terms. Use contact details obtained independently from a reliable source rather than relying only on a phone number or link supplied in a suspicious message.
If the company makes a claim about a license, verify it with the relevant regulator. If it claims to be connected to another business, confirm that relationship through reliable evidence.
Be wary if you receive contradictory answers, face pressure to act immediately, or are asked to pay an unexplained fee before you can withdraw money.
What if you have already sent money or shared sensitive details?
Your next step depends on what happened.
- You sent money: Contact your bank, card issuer, or payment provider promptly. Explain the transaction and ask whether it can be stopped, disputed, or reviewed.
- You shared a password: Change it immediately, especially if you use it on other accounts. Enable multifactor authentication where available.
- You shared identity documents: Contact the relevant identity, banking, or credit-reporting services in your country to ask what protective steps are available.
- You suspect fraud: Preserve emails, messages, receipts, transaction references, and website addresses. Report the incident to the appropriate financial regulator or law-enforcement channel.
Do not send more money simply because someone promises to recover your previous payment for an upfront fee. Recovery scams often target people who have already lost money.
The answer: Unverified information is a reason to pause, not a reason to guess. If money or personal data is already involved, contact the relevant financial institution or service provider as soon as possible.
Frequently Asked Questions About MyFastBroker.com
Is MyFastBroker.com a scam?
The website’s name or appearance alone cannot establish that it is a scam. A fair assessment requires evidence about its operator, activities, claims, and any financial services it promotes. Treat unverified details as unresolved rather than assuming either fraud or complete safety.
Can you trade stocks directly on MyFastBroker.com?
The website’s contact page says it does not open accounts, execute trades, or manage funds. Based on that published statement, it presents itself as an informational resource rather than a direct trading platform. Check its current official pages for any changes before relying on that description.
Is MyFastBroker.com connected to similarly named websites?
Do not assume that two websites belong to the same company because their names look alike. Compare the exact domain, legal disclosures, and independently verifiable ownership information. A different domain ending, such as .net instead of .com, is not proof of a connection.
Is HTTPS enough to prove that a financial website is safe?
No. HTTPS helps protect the connection between your browser and a website. It does not establish the operator’s identity, prove regulatory registration, or guarantee that a financial offer is legitimate.
What should you do before using a financial provider recommended by the site?
Identify the provider’s legal name, check its relevant registration where required, read its current fees and terms, and confirm that you are using its genuine website. If an important detail remains unclear, wait until you can verify it.
Final takeaway
MyFastBroker.com should be assessed by what its published pages say, what its services actually do, and what independent evidence can confirm. Its website description can help you understand its intended role, but it should not replace checks on any financial company you may choose to use.
Honestly, the safest approach is straightforward: understand who you are dealing with, verify important claims, read the terms before sharing information, and do not send money when the provider’s identity or offer remains unclear.
Note: This article describes the available website information and general verification methods. It does not certify MyFastBroker.com or any third-party provider as safe, licensed, or fraudulent.